 admin
Planning a trip often involves significant financial investment and excitement, but unforeseen circumstances can quickly turn anticipation into anxiety. This is where a Cancel For Any Reason (CFAR) Travel Insurance Policy offers an unparalleled layer of protection, providing peace of mind against life’s unpredictable twists.
Unlike standard travel insurance, CFAR allows travelers to cancel their trip for virtually any reason, ensuring a reimbursement of a significant portion of their non-refundable expenses. This comprehensive guide will delve into the intricacies of CFAR policies, explaining their benefits, requirements, and suitability for various travelers.
What is Cancel For Any Reason (CFAR) Travel Insurance?
A Cancel For Any Reason (CFAR) travel insurance policy is an optional upgrade or rider that can be added to a standard travel insurance plan, offering the ultimate flexibility for trip cancellations. It provides reimbursement for a percentage of your non-refundable trip costs, regardless of the reason for cancellation. This stands in stark contrast to traditional travel insurance, which only covers cancellations due to a specific list of ‘covered reasons.’
This type of policy is designed to protect travelers from financial loss in situations where their reasons for canceling fall outside the narrowly defined scope of standard policies. Whether you simply change your mind, fear political unrest, or face an unexpected work conflict, CFAR gives you the power to cancel without losing everything. The flexibility offered by a CFAR Travel Insurance Policy makes it a powerful tool for modern travelers navigating an uncertain world.
Distinguishing CFAR from Standard Trip Cancellation Coverage
The fundamental difference between CFAR and standard trip cancellation insurance lies in the scope of covered reasons. Standard policies typically enumerate a specific list of perils, such as illness, injury, death of a family member, severe weather, or acts of terrorism, for which cancellation is covered. If your reason for cancelling is not on that list, you are not eligible for reimbursement.
Conversely, a Cancel For Any Reason (CFAR) Travel Insurance Policy removes these stringent limitations, allowing you to cancel for any reason not explicitly excluded by the policy. This broad coverage means that personal preference, fear of travel, or a simple change of plans become valid reasons for claiming reimbursement. The elevated flexibility, however, usually comes with a higher premium and a partial reimbursement percentage, typically ranging from 50% to 75% of your insured trip costs.
Why Should You Consider a CFAR Policy?
Opting for a CFAR policy can be a wise decision for a variety of travelers and trip scenarios. Its primary appeal is the unparalleled sense of security it offers, knowing that your significant financial investment in a trip is protected no matter what arises.
Many travelers choose CFAR when they anticipate potential personal or global uncertainties that might impact their travel plans, such as health concerns, volatile geopolitical situations, or highly non-refundable bookings. It empowers you to make travel commitments with confidence, understanding that you retain the option to adjust or cancel if circumstances dictate.
Peace of Mind Against the Unpredictable
Life is full of unexpected events, and a CFAR policy directly addresses this inherent unpredictability. It shields you from the financial repercussions of last-minute changes, personal emergencies, or even a simple desire to postpone your adventure. This freedom from worry allows you to book flights and accommodations months in advance without feeling locked into an unalterable plan.
With a Cancel For Any Reason (CFAR) Travel Insurance Policy, the stress of needing to justify your cancellation to an insurer is eliminated, simplifying a potentially complicated process. It essentially transfers the risk of personal indecision or unforeseen non-covered events from your shoulders to the insurance provider, albeit for a percentage of the cost.
Key Features and Requirements of CFAR Policies
While CFAR policies offer broad protection, they come with specific requirements that must be met to ensure eligibility and coverage. These conditions are standard across most providers and are crucial for travelers to understand before purchasing.
Adhering to these requirements is essential for a successful claim and to maximize the benefits of your Cancel For Any Reason (CFAR) Travel Insurance Policy. Failing to meet them could invalidate your coverage, resulting in financial loss despite having purchased the policy.
Strict Purchase Window
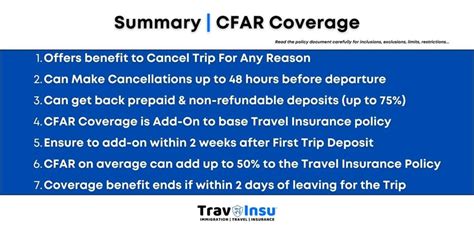
One of the most critical requirements for CFAR coverage is the limited purchase window. Most insurance providers mandate that you buy the CFAR add-on within a short period, typically 10 to 21 days, from your initial trip deposit or payment. This early purchase window is designed to prevent travelers from buying insurance only when a potential cancellation event seems imminent.
Missing this crucial deadline will generally disqualify you from adding CFAR to your policy, even if you still wish to purchase standard travel insurance. Therefore, if you are considering a Cancel For Any Reason (CFAR) Travel Insurance Policy, it is imperative to act quickly after making your first trip payment.
Insuring All Non-Refundable Trip Costs
To qualify for CFAR coverage, you are typically required to insure 100% of your non-refundable trip costs. This means you cannot selectively insure only certain components of your trip; all prepaid, non-refundable expenses must be included in the total insured amount.
If you add new non-refundable expenses to your trip after the initial purchase, you might need to update your policy and pay additional premiums to maintain full CFAR eligibility. This ensures that the insurer accurately assesses the total risk and prevents travelers from underinsuring their trip components.
Adhering to Cancellation Deadlines
Even with CFAR coverage, there is a deadline by which you must cancel your trip to be eligible for reimbursement. Most policies require cancellation at least 48 to 72 hours prior to your scheduled departure date. Cancelling within this window allows the insurance company to process your claim properly.
Attempting to cancel your trip just hours before departure, or after the trip has already begun, will likely render your CFAR coverage invalid. Always review your policy document for the exact cancellation timeframe to ensure compliance.
Understanding Reimbursement Percentages
It is crucial to understand that CFAR policies do not offer a 100% reimbursement of your trip costs. Typically, these policies reimburse between 50% and 75% of your insured non-refundable expenses. The exact percentage varies by provider and policy.
This partial reimbursement reflects the broader coverage scope and increased risk undertaken by the insurer. While not a full refund, receiving 50-75% back significantly mitigates your financial loss compared to losing 100% of your trip investment.
Who Should Buy CFAR Travel Insurance?
A Cancel For Any Reason (CFAR) Travel Insurance Policy is not for every traveler, but it provides exceptional value for specific individuals and situations. Understanding if you fall into these categories can help you decide if the added cost is justified.
Consider your personal circumstances, the nature of your trip, and your risk tolerance when evaluating the suitability of a CFAR policy for your travel plans. It’s an investment in flexibility and security, which holds different values for different people.
High-Value Trips with Significant Non-Refundable Expenses
Travelers booking expensive trips, especially those with substantial non-refundable deposits for tours, cruises, or luxury accommodations, are ideal candidates for CFAR. The potential financial loss from cancelling such trips without CFAR can be devastating.
For example, a multi-country European tour or an Antarctic expedition often involves tens of thousands of dollars in upfront, non-refundable payments. A CFAR policy provides a vital safety net for these significant investments.
Individuals with Unpredictable Schedules or Health Concerns
People whose work schedules are prone to sudden changes or who have family members with fluctuating health conditions might find CFAR invaluable. These personal circumstances often fall outside the ‘covered reasons’ of standard policies, making CFAR the only viable option for protection.
Expecting parents, individuals in demanding professions, or those caring for elderly relatives can particularly benefit from the flexibility to cancel without specific justification. A CFAR policy allows them to plan trips without fearing irreversible commitments.
Travelers Concerned About Non-Specified Risks
In an era of global uncertainty, many travelers are concerned about risks not typically covered by standard insurance, such as civil unrest, travel advisories, or new pandemic outbreaks that do not meet ‘epidemic’ criteria. CFAR addresses these broader anxieties.
The psychological comfort of knowing you can cancel due to general fear of travel, even if official warnings aren’t issued, is a significant benefit for many. It empowers travelers to prioritize their personal safety and comfort above all else.
Understanding the Cost of CFAR
As an enhanced level of protection, a Cancel For Any Reason (CFAR) Travel Insurance Policy inherently comes at a higher premium than standard travel insurance. This increased cost reflects the significantly broader coverage it provides and the higher risk the insurer assumes.
Typically, adding CFAR can increase the cost of your travel insurance by 40% to 60% above the base premium. While this may seem substantial, many travelers view it as a worthwhile investment for the unparalleled flexibility and peace of mind it delivers.
Factors Influencing CFAR Premiums
Several factors contribute to the overall cost of a CFAR policy. The total non-refundable cost of your trip is the primary determinant, as the reimbursement percentage is applied to this amount.
Other influential factors include the age of the travelers, the duration of the trip, and the destination. Older travelers and longer, more complex trips often incur higher premiums due to increased inherent risks.
The CFAR Claim Process
While the reasons for cancellation are flexible with CFAR, the claim process itself still requires adherence to specific steps and documentation. Understanding this process in advance can expedite your reimbursement.
It is important to gather all necessary information and submit it promptly according to your policy’s guidelines. This systematic approach ensures a smoother and more efficient resolution of your claim.
Required Documentation and Notification
When filing a CFAR claim, you will typically need to provide proof of your initial trip payments and confirmation of your trip cancellation from all travel providers (airlines, hotels, tour operators). Documentation of any refunds received from these providers is also necessary.
You must also formally notify your insurance provider of your intent to cancel and file a claim within the timeframe specified in your policy, often within a few days of your cancellation. Keep clear records of all communications and documents related to your trip and claim.
Potential Limitations and Exclusions
Despite its broad coverage, a Cancel For Any Reason (CFAR) Travel Insurance Policy is not without its limitations and specific exclusions. It is vital to read the policy document thoroughly to understand exactly what is and isn’t covered.
Being aware of these caveats will prevent misunderstandings and ensure that your expectations align with the policy’s actual provisions. Always clarify any uncertainties with your insurance provider before purchasing.
Not 100% Reimbursement
As previously mentioned, the most significant limitation is that CFAR policies do not offer a full refund; reimbursement is typically limited to 50% to 75% of your insured trip cost. This means you will still incur some financial loss, even with CFAR coverage.
Travelers expecting a complete recoupment of their investment might be disappointed if they do not fully understand this fundamental aspect of CFAR. The benefit lies in recovering a substantial portion, not the entirety, of your expenses.
Geographical and Age Restrictions
Some CFAR policies may have geographical restrictions, limiting coverage to certain countries or regions. Additionally, specific age limits might apply, making CFAR unavailable for very young or very elderly travelers in some cases.
These restrictions are less common but can appear in certain plans or with specific providers. Always confirm that your destination and age group are eligible for the CFAR policy you are considering.
Is CFAR Worth the Investment?
Deciding whether a Cancel For Any Reason (CFAR) Travel Insurance Policy is worth the additional cost depends heavily on individual circumstances, risk tolerance, and the nature of the trip. For some, the added premium is a small price for immense peace of mind.
For others, especially those with very low-cost or easily refundable trips, the expense of CFAR might outweigh its potential benefits. A careful cost-benefit analysis is essential for making an informed decision tailored to your specific travel needs.
Weighing Cost Against Peace of Mind
The primary argument for CFAR is the unparalleled flexibility and psychological comfort it offers, allowing you to book confidently. This peace of mind is subjective, but for many, it justifies the higher premium, especially for milestone trips or travel during uncertain times.
Consider the potential financial loss if you had to cancel without CFAR versus the added premium. If the premium is a small percentage of a significant potential loss, CFAR often presents a compelling value proposition.
Tips for Purchasing a CFAR Policy
If you’ve decided that a Cancel For Any Reason (CFAR) Travel Insurance Policy is right for you, there are several steps you can take to ensure you get the best coverage for your needs. Diligence in research and understanding policy details is paramount.
These tips will help you navigate the purchasing process effectively, ensuring you secure a policy that truly protects your travel investment.
Compare Quotes and Providers
Always compare CFAR quotes from multiple reputable travel insurance providers. Different companies may offer varying reimbursement percentages, premium costs, and specific terms and conditions for their CFAR riders.
Utilize online comparison tools or consult with an independent insurance agent specializing in travel insurance to find the most suitable policy. This allows for a comprehensive overview of your options and helps you identify the best value.
Read the Policy Document Carefully
Before finalizing your purchase, meticulously read the entire policy document, paying close attention to the CFAR rider’s specific terms, conditions, and exclusions. Understand the exact reimbursement percentage, the cancellation deadline, and any other unique requirements.
Do not hesitate to contact the insurance provider directly if you have any questions or require clarification on any aspect of the policy. A thorough understanding prevents future surprises or disputes during the claim process.
Ensure All Non-Refundable Costs Are Included
Double-check that every non-refundable component of your trip, including flights, accommodation, tours, and cruises, is accurately accounted for in your total insured amount. Underinsuring your trip will reduce your potential reimbursement.
If your trip plans change and new non-refundable expenses are added, promptly contact your insurer to update your policy and ensure these new costs are covered under your CFAR rider. This continuous monitoring is vital for complete protection.
Conclusion
A Cancel For Any Reason (CFAR) Travel Insurance Policy stands as a powerful tool in modern travel planning, offering unparalleled flexibility and significant financial protection against life’s uncertainties. While it comes with a higher cost and partial reimbursement, its ability to cover nearly any reason for cancellation provides invaluable peace of mind for many travelers. By understanding its features, requirements, and limitations, you can make an informed decision about whether CFAR is the right investment for your next adventure, ensuring your travel dreams remain protected.
Frequently Asked Questions (FAQ)
What is the main difference between CFAR and standard travel insurance?
The main difference is the scope of covered reasons for cancellation. Standard travel insurance only covers cancellations due to a specific list of defined perils (e.g., illness, death, natural disaster). CFAR, or Cancel For Any Reason, allows you to cancel your trip for virtually any reason not explicitly excluded by the policy, offering much broader flexibility.
How much of my trip cost will CFAR reimburse?
CFAR policies typically reimburse a percentage of your non-refundable trip costs, usually ranging from 50% to 75%. It does not provide a 100% refund, so you will still incur some financial loss, but a significant portion of your investment will be recovered.
When do I need to purchase CFAR insurance?
Most CFAR policies require you to purchase the coverage within a strict timeframe, usually 10 to 21 days, from your initial trip deposit or first payment. Missing this deadline will often make you ineligible for CFAR coverage.
Can I cancel for any reason, literally any reason?
Yes, for virtually any reason that isn’t explicitly excluded by the policy. This includes personal preference, fear of travel, work conflicts, or simply changing your mind, reasons which are typically not covered by standard travel insurance policies. However, there are still specific deadlines, such as cancelling 48-72 hours before departure.
Is CFAR insurance always more expensive?
Yes, CFAR insurance is always more expensive than standard trip cancellation coverage due to its significantly broader scope of coverage. It typically adds 40% to 60% to the cost of a basic travel insurance policy.
Are there any trips CFAR insurance doesn’t cover?
While CFAR is broad, some policies might have geographical restrictions or specific exclusions, especially for certain high-risk activities or destinations. Additionally, you are usually required to insure 100% of your non-refundable trip costs for CFAR to apply, and there’s always a specific deadline to cancel the trip (e.g., 48-72 hours prior to departure).
What documents do I need to make a CFAR claim?
To make a CFAR claim, you will typically need proof of your initial trip payments, official confirmation of your trip cancellation from all relevant travel providers (e.g., airline, hotel), and documentation of any refunds received directly from those providers. You also need to notify your insurance provider of the cancellation and claim within the timeframe specified in your policy.